Analysis: Malawi’s forex squeeze exposes the limits of stabilisation without liquidity
Dalitso Kabambe, the former central bank governor who now leads the opposition UTM party, has put his finger on something Malawi’s official statistics tend to understate: a currency can look “stable” on paper while remaining acutely scarce in practice.
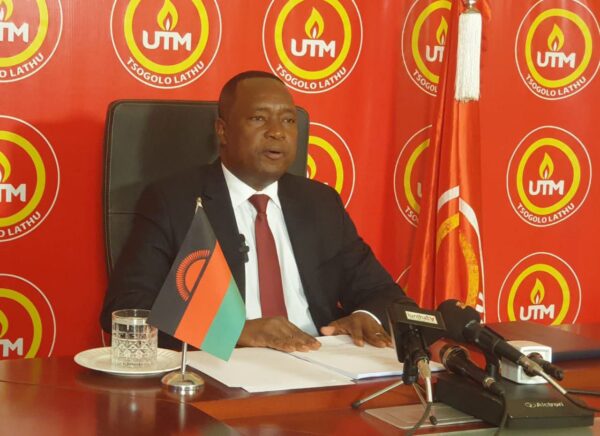
His warning that commercial banks are now capping individual foreign-exchange disbursements at just $200 is a useful corrective to the more sanguine reading of Malawi’s macroeconomic position offered elsewhere — including in the government’s own year-one report card, which points to easing inflation, steadier food prices and consistent fuel supply as evidence of a corner turned.
Both things can be true at once.
Headline inflation and exchange-rate stability are typically the first indicators to respond to disciplined monetary and fiscal management — reduced government borrowing pressure, a credible IMF negotiating track, tighter spending.
But those indicators describe the price of foreign currency, not its availability.
A central bank can hold a rate steady while the actual stock of dollars circulating through the banking system remains critically thin, particularly in an economy as import-dependent as Malawi’s, where fuel, pharmaceuticals and industrial inputs are priced and settled in hard currency regardless of what the kwacha is doing.
Kabambe’s specific claim — that banks are struggling to liquidate outstanding Letters of Credit — is the more technically significant part of his intervention, and worth taking seriously independent of its political framing.
An LC is, in effect, a bank’s promise to pay a foreign supplier once goods are shipped or received; if banks cannot settle those obligations, it signals not a temporary cash-flow wrinkle but a structural mismatch between the foreign-currency liabilities the banking sector has already committed to and the foreign-currency assets it actually holds.
That has second-order effects that outlast any single quarter: suppliers begin demanding payment upfront rather than extending trade credit, import costs rise to compensate for settlement risk, and businesses that depend on imported inputs — which in Malawi is most of the formal manufacturing and retail sector — face a financing bottleneck that has nothing to do with their own creditworthiness.
His broader point about the limits of relying on commercial banks to drive recovery is also, in narrow technical terms, correct, if somewhat self-evident: banks intermediate deposits, they do not create foreign currency, and their willingness to extend forex-denominated credit in a thin-liquidity environment will always be constrained by prudential considerations and shareholder interests rather than developmental ones.
That is not a criticism of the banks so much as a description of what commercial banking is for. It does, however, sharpen the question of where additional dollar liquidity is meant to come from if not the banking sector — official reserves, remittance inflows, export receipts, or external financing — and whether the pace of the IMF programme renegotiation the government has pointed to as a stabilisation win is fast enough to close that gap before it does more damage to private-sector activity.
On government borrowing, Kabambe’s crowding-out argument is standard fiscal economics rather than a novel claim, but it lands with particular force in Malawi’s specific circumstances.
High domestic borrowing costs draw commercial bank balance sheets toward government paper and away from private lending — precisely the dynamic that would compound, rather than offset, a foreign-currency-driven credit squeeze.
If banks are simultaneously capital-constrained on the forex side and incentivised to hold government debt on the kwacha side, the private sector faces a pincer: it cannot easily get dollars, and it cannot easily borrow kwacha either.
None of this amounts to a wholesale rebuttal of the government’s stabilisation narrative — inflation easing and fuel supply normalising are genuine achievements that matter to ordinary households in the near term.
But Kabambe’s intervention, coming from a former Reserve Bank governor rather than a purely political critic, is a reminder that macroeconomic stabilisation and foreign-currency liquidity are related but distinct problems, and that solving the first does not automatically solve the second.
For a government whose own assessors have already flagged that investment pledges have yet to translate into jobs, a forex market this constrained is not a footnote to that story — it may be a significant part of the explanation for it.
Follow and Subscribe Nyasa TV :